Most investors who look at assisted living see a demographic story. The first baby boomers turned 80 this year, and there aren’t enough beds waiting for them. But the other half of the story gets less attention. The banks that used to finance these communities have pulled back just as that demand arrives.
Strong demand and scarce financing make assisted living a sector that needs new capital, which is why it has investors’ attention right now. The catch is that demand alone won’t carry a poorly run community, so where your money goes matters as much as the sector itself. We’ll walk through how assisted living works as a business, why the timing looks different right now, and what to ask before you commit.
Assisted living earns its money from care, and that shapes your risk
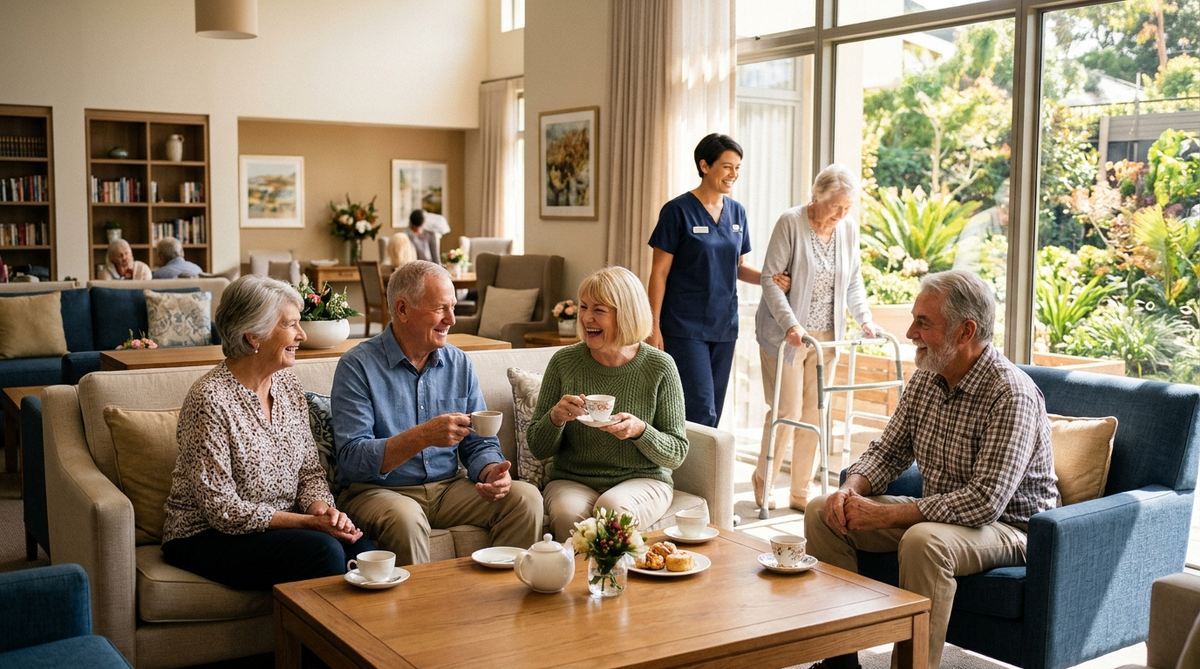
An assisted living community looks like an apartment building from the parking lot. Inside, it runs on daily care, and that’s what makes it a different kind of investment.
What is assisted living, and how is it different from a nursing home?
Assisted living is a residential community for older adults who need help with everyday tasks like bathing, dressing, and managing medications, but who don’t need round-the-clock medical care. Residents usually have their own apartments, share meals in a common dining room, and can reach a caregiver day or night. Each state licenses these communities under its own rules.
A nursing home provides skilled medical care and costs considerably more. The national median for assisted living reached $6,200 a month in 2025, compared with roughly $9,600 for a semi-private nursing home room.
Who pays for assisted living?
Mostly, residents and their families do. Most assisted living residents use private funds, such as personal savings or long-term care insurance, to cover their costs.
Government programs play a much smaller role. Medicaid helps about 17% of residents pay for daily care services, but it doesn’t cover room and board. And Medicare doesn’t cover assisted living at all.
For an investor, the fact that families pay most of the bill has benefits and drawbacks. The benefit: so little revenue comes from government programs that a change in Medicare or Medicaid policy is unlikely to upend a community’s finances. The drawback: what local families can afford sets a ceiling on what a community can charge. If costs like caregiver wages rise faster than families can absorb, the community can’t simply raise its rates to cover the difference, and that squeeze on margins is a real risk to watch.
What decides whether a community does well?
Families usually choose a community close to where they live, so location is what gets them in the door. Whether residents stay, and whether new ones keep coming, depends on the team running it: caregivers who show up every shift, a director who keeps the state license in good standing, and steady relationships with the hospitals and doctors who refer new residents.
When those pieces work, rooms fill and families stay. When they don’t, a beautiful building in a growing market can still struggle.
Assisted living demand is growing on a schedule you can see coming
Most real estate demand rises and falls with the economy, while assisted living demand follows more of a set timeline. The 80-and-older population is projected to double, from 14.7 million in 2025 to 29.4 million by 2045, and 80 is the age the industry has long treated as the front edge of senior housing demand.
You can already see it in the numbers. Assisted living occupancy reached 89.1% in the third quarter of 2026, up from 88.3% the quarter before. Overall, senior housing occupancy has now risen for 21 quarters in a row. Those numbers can vary a lot by city, though: Boston’s senior housing occupancy hit 94% in the third quarter of 2026, compared with 86.5% in Miami.
That spread is a useful reminder. A strong national trend doesn’t fill a specific building. Whether a particular community fills up depends on its own market and the team running it.
Building and lending haven’t kept up, and that’s where the opportunity is
New supply isn’t arriving fast enough to meet the demand. Senior housing inventory growth stayed below 1% for the sixth straight quarter, and at the current pace of development, the country is on track to be 550,000 senior housing units short by 2030. That gap represents roughly $275 billion in investment that hasn’t happened yet.
At the same time, the usual sources of money have stepped back. Banks have pulled back from senior housing lending, and institutional investors, private equity firms, REITs, and private lenders are moving into the space they left.
From where we sit, most of the strain in this sector right now comes from how communities were financed. Owners who took on short-term or variable-rate loans when borrowing was cheap are feeling the pressure now that rates are higher, even when their rooms are full. That leaves a real need for lenders who can tell a sound project from a shaky one.
We’re also watching a wave of new money arrive from investors and operators whose experience is in apartments. Many of them understand the demand, but fewer understand what it takes to run a care business, and that’s where a lot of avoidable mistakes start.
Four ways to invest in assisted living, and who you’re relying on in each
There are four main ways to invest in assisted living, the same routes you’d consider for senior housing in general. The biggest difference between them is who has to get things right for you to get paid: you, an operator running one building, the stock market, or a borrower keeping up with loan payments.
- Residential assisted living home: you buy a property, get it licensed, and run it (or hire someone to) as a care home for residents. It offers the most control and upside for someone who wants to build a care business.
- **Syndication:** you pool money with other investors to buy one community, managed by a sponsor and run by an operator. It can pay well when a strong operator keeps the community full.
- Public healthcare REIT: you buy shares in a public company that owns many senior housing properties, the same way you’d buy any stock. You get broad exposure and can sell any day, with stock market swings attached.
- Private lending fund: you put money into a fund that lends to owners and operators and earns interest on those loans. You give up the equity upside, and a fund spread across many loans doesn’t hinge on any one community hitting its projections.
| Route | Who you’re relying on | How involved you are | Getting your money out |
|---|---|---|---|
| Owning a small residential assisted living home | Your ability to staff, license, and fill the home | Very involved: you’re running a care business | Selling the property or the business |
| Equity in a single community (syndication) | One operator filling one building, then a profitable sale | Hands-off, but your outcome rides on that operator | Usually locked until the sponsor sells, often several years |
| Public healthcare REITs | Dividends, plus the stock market’s daily pricing of the shares | Hands-off | Sell shares on any trading day |
| Private lending fund | Borrowers making their loan payments, with the property as collateral | Hands-off | Set by the fund’s terms, which vary widely |
Five questions that separate a strong assisted living investment from a risky one
Whichever route you choose, these questions apply. They work for a pitch deck, a fund, or any private real estate investment that touches senior care, including a conversation with us.
1. Who runs the care, and have they done it in this market? Experience in apartments or even independent living doesn’t carry over cleanly to assisted living. Ask how many assisted living communities the operator runs nearby and how long their community directors have stayed in place.
- . How quickly did the community fill, and does it stay full? Ask for occupancy history, not just today’s number. A community that took three years to fill and one that filled in one year are telling you very different things about local demand.
3. Can the people paying the bill keep paying it? With most residents paying privately, the monthly rate has to fit what families in that area can afford. A high-end community in a modest-income town carries real risk, no matter how good the building looks.
4. What happens to your money in a bad quarter? Every community has slow stretches: a staffing gap, a slower move-in season, a surprise repair. Ask how much room exists between what the project is expected to earn and what you’re owed, and whether reserves are set aside for exactly these moments.
5. Who takes a loss before you do? Find out where you stand if something goes wrong. Ask whether the sponsor has its own money in the deal, who gets paid first, and whether the sponsor can step in and replace an operator who isn’t performing.
The strongest answers usually come from people who know how to judge a care operator and how to structure the money behind the deal. Plenty of firms can do one. Far fewer can do both.
Freedom Notes: Investing in assisted living without betting on one building
With Freedom Notes, investors lend to our fund, and we lend that money to owners and operators of senior housing, apartments, and self-storage. In a sector that needs capital, our job is to be careful about who gets it. Here’s how that approach answers the five questions above.
You get a partner who judges the operator before the building. In the communities we finance, the care is run by specialist operators. Our job is to decide which of them earn our capital. Every borrower goes through our 44-point vetting process, which covers licensing and legal risk along with the property itself, and we’ve walked away from deals days before closing when something didn’t hold up.
Income designed to hold steady even when one property has a slow quarter. We aim to lend where a project is planned to earn roughly 20% to 22%, while note investors may target 8% to 14%. That spread, along with reserves we keep for lean stretches, is designed to absorb a late lease-up or a jump in staffing costs before it reaches your return. All investments in private placements involve risk, including possible loss of principal.
A deal has to work for you before it works for us. Our own capital is in the deals alongside yours, and our structure is designed so FFI is paid after our note investors. We also set up our lending so we can step in and take over a project if a partner can’t carry it forward.
One rough patch doesn’t sink your whole investment. Your money is spread across senior housing, apartments, and self-storage, in different markets and with different operators. If one community struggles, it’s one piece of the picture.
Taxes and exits stay simple. Interest is reported on a 1099 rather than a K-1, which keeps tax season more manageable. You can also exit once a year, starting in year one. Talk with your tax advisor about how that fits your situation.
Through more than 17 years of operating, FFI has had no missed investor payouts to date, according to Freedom Family Investments. Past performance does not guarantee future results.
Who this may not be right for
A lending position in assisted living isn’t the right fit for everyone.
If you want to own and run an assisted living home yourself, direct ownership gives you the control a fund can’t. You’ll take on the staffing, licensing, and liability that come with it.
If you want to share in the gains when a single community turns around, an equity position is built for that. A note pays the same return whether a property doubles in value or holds steady.
If you’re counting on depreciation to lower your tax bill, ownership or equity will do more for you than interest income reported on a 1099.
And if you need to reach your money on short notice, a public REIT you can sell any trading day is a better match than an annual exit window.
Wondering whether assisted living belongs in your portfolio?
If you’re weighing assisted living and want to talk it through, we offer a 30-minute conversation with our team. We’ll walk you through how we approach senior housing lending, how Freedom Notes are structured, and answer whatever questions you bring.
It isn’t a sales call. The goal is to help you understand how Freedom Notes work and give you an honest read on whether this fits your situation, even if the answer is no.