Bonds are the first place most people look when they want steady, predictable income. And for protecting what you already have, they deliver. The question isn’t whether bonds are useful. It’s whether they’re doing everything an income-focused investor needs them to do.
If you need your capital to grow, there are fixed-income structures that target higher returns on a set schedule, and many accredited investors don’t realize they qualify for them.
Bonds earn their reputation for a reason
Bonds deserve their place in a portfolio, and it’s worth understanding what they do well before asking where they fall short.
When you buy a bond, you’re lending money to a government or a corporation. In return, they pay you interest on a set schedule and return your principal when the bond matures. That structure gives investors something genuinely valuable: predictability. You know what you’ll earn, you know when you’ll get paid, and at maturity, you get your principal back.
U.S. Treasury bonds carry the full backing of the federal government, which makes them one of the lowest-risk investments available. A 10-year Treasury currently yields around 4.7%, while investment-grade corporate bonds yield roughly 5% to 5.5% in exchange for taking on the credit risk of the issuing company. Both trade on public exchanges, which means you can sell before maturity if you need to.
For investors whose primary goal is preserving capital and reducing volatility, bonds do that job well. They can serve as ballast in a portfolio heavy on stocks, smoothing out the swings during periods of market stress. That role is real, and it matters.
What a 4.7% yield actually earns you after inflation
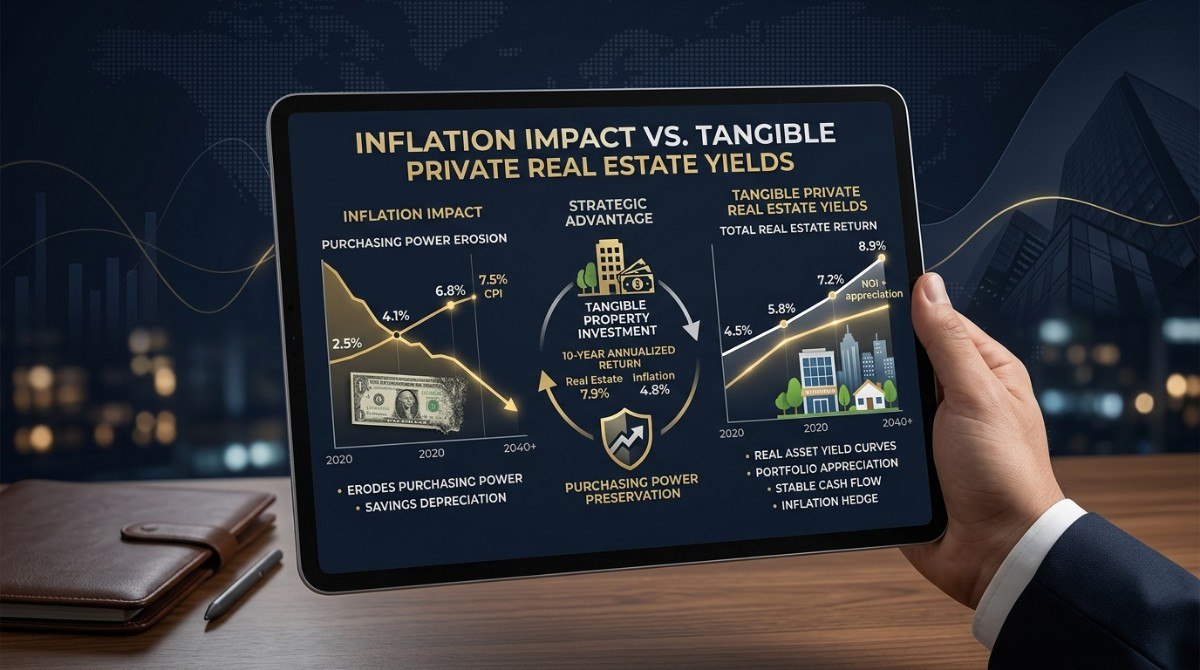
At first glance, today’s bond yields look better than they have in over a decade.
But yield isn’t the full picture. What matters for an investor’s purchasing power is what’s left after inflation. With the annual inflation rate at 3.5% as of the most recent data, a 10-year Treasury yielding 4.7% is delivering a real return of roughly 1.2%. For investors trying to build wealth or generate meaningful income from their capital, that’s a thin margin to work with.
Bonds also carry risks that aren’t always obvious.
Rising interest rates can work against you. If you hold a bond paying 4% and new bonds start paying 5%, you’re locked into the lower rate until maturity. If you need to sell early, it’s worse: no buyer will pay full price for a 4% bond when they can get 5%, so you sell at a discount and take a real loss.
Reinvesting at maturity means accepting whatever rate is available. When your bond matures, the new rate might be lower than what you were earning. Your income drops, and there’s nothing you can do about it.
None of these risks make bonds a bad investment. But for accredited investors whose goal is generating real, after-tax income that preserves or grows their purchasing power over time, bonds may be doing only part of the job.
Fixed-income options most accredited investors don’t know they qualify for
Most people stop at bonds when they think about fixed income. They decide they want predictable income, they buy bonds, and they move on. That’s a reasonable approach. It’s leaving opportunity on the table.
“Fixed income” is an investment approach, not a specific product. It means an investment that pays you a predictable return on a defined schedule. Bonds fit that definition. So do several other types of investments that work very differently under the surface.
Municipal bonds offer income that may be exempt from federal taxes, and in some cases state taxes as well. For high-income investors in high-tax states, the after-tax yield on a muni can compete with or exceed a Treasury. The trade-off is that yields are typically lower on a pre-tax basis, and the market is less liquid than Treasuries or corporates. Consult your tax advisor.
Private credit is lending to businesses or projects outside the traditional banking system. These are typically available only to accredited investors, and because the loans aren’t publicly traded, they often target higher yields than public bonds. The trade-off is less liquidity and more reliance on the firm running the fund to evaluate borrowers well.
Real estate-backed debt is lending secured by physical property. Like bonds, you earn a fixed return on a defined schedule, but your investment is backed by a tangible asset rather than a government promise or a corporate balance sheet. Because these investments are private and less liquid, they can target yields well above what public bonds offer. The trade-off is that your capital is typically committed for a defined term with limited exit options.
For accredited investors who are already investing beyond stocks and bonds, understanding the full range of fixed-income options is one of the clearest ways to make more informed decisions about where their income actually comes from.
Four questions that reveal whether a fixed-income investment deserves your capital
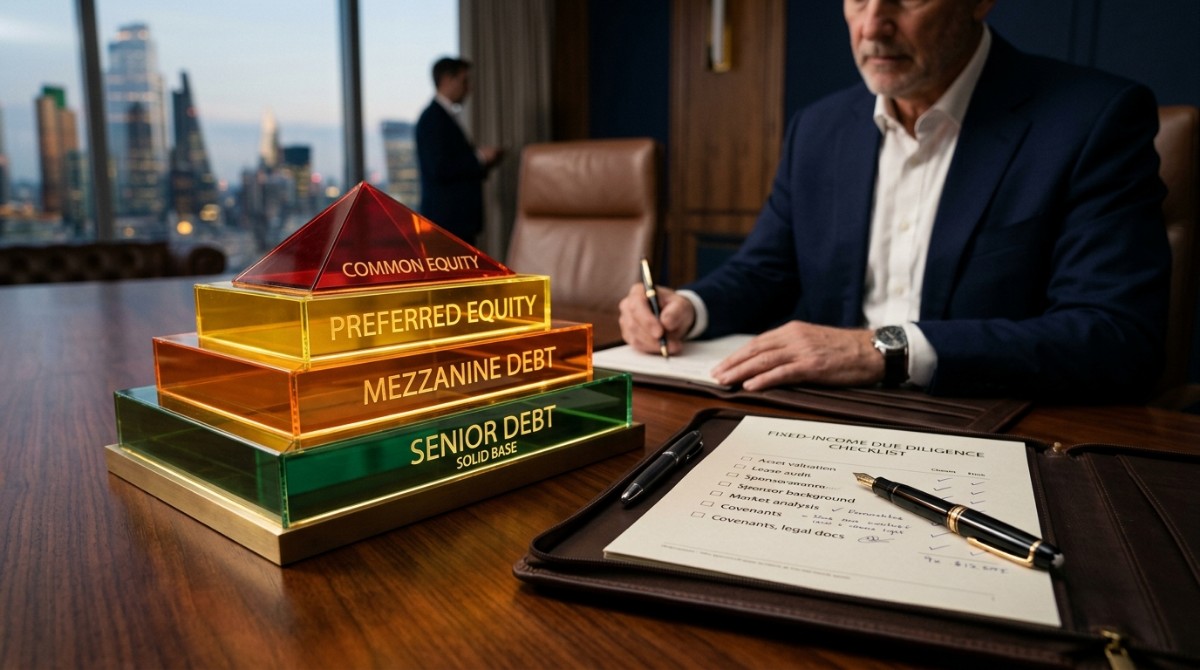
Whether you’re evaluating a Treasury bond, a corporate note, or a private real estate lending structure, the same core questions apply. The answers just look different depending on the investment.
What are you earning, and what’s behind it? Start with the yield itself and compare it to what you’d earn from Treasuries or investment-grade corporate bonds. Then look at what’s backing that return. A Treasury is backed by the federal government. A corporate bond depends on the company’s ability to generate profit. A real estate-backed note is secured by physical property. The higher the yield relative to Treasuries, the more important it is to understand exactly what’s supporting it.
Where do you stand in line? If a deal loses money, who takes the hit first? In some structures, the investor lending money gets paid before the investors who own the property. That means the ownership side absorbs losses before the lending side does. In others, you’re the owner, and you’re first in line for both the upside and the downside.
What’s the term, and how do you get your money back? Bonds can be sold on the open market before maturity, but the price you get depends on market conditions. Private fixed-income investments typically have defined terms and less liquidity. Neither is automatically better, but the trade-off between flexibility and return is worth understanding clearly.
How will the income be taxed? Bond interest is taxed as ordinary income, while municipal bond interest may be exempt from federal taxes. Some private structures report income on a 1099, others on a K-1. Tax treatment can meaningfully affect the net return, and high-income investors should factor that in from the start. Consult your tax advisor.
Freedom Notes: predictable income designed to grow your wealth, not just protect it
We built Freedom Notes for investors who want their fixed-income allocation to do more than preserve capital. Bonds can protect what you have. Flagship Notes are designed to help grow it.
Yields that target meaningful income, not just preservation. Investors may target 8% to 14%* annually, depending on the offering. Compare that to the 4.7% on a 10-year Treasury or the 5% to 5.5% on investment-grade corporate bonds. These investments are not risk-free and involve the potential loss of principal.
Your rate is set upfront and doesn’t change. One of the biggest risks with bonds is that rising rates can lock you into a lower yield or force you to sell at a loss. With Flagship Notes, the rate you agree to is the rate you earn, and your return isn’t subject to repricing during the term of your investment.
An annual exit, not a decade-long lockup. Most private fixed-income investments lock your capital in for five to ten years. Flagship Notes offer an annual exit option, so investors can request their capital back at the end of any year.
We’ve been operating for more than 17 years, with no missed investor payouts to date, according to Freedom Family Investments. Past performance does not guarantee future results.
As with any private investment, Flagship Notes involve risk, including illiquidity and the potential loss of principal. These are not publicly traded securities, and investors should review all offering materials carefully before investing.
When bonds or another structure may be a better fit
Not every investor is looking for what Flagship Notes are designed to deliver, and being honest about that matters more than trying to make the match work.
If you need daily liquidity and want the ability to sell at any time, a publicly traded bond or Treasury position may be a better fit. Flagship Notes offer an annual exit, but that’s not the same as a bond you can sell tomorrow.
If your primary goal is maximizing upside and you’re comfortable taking equity risk to get there, a fixed-return structure isn’t designed for that. An equity fund or direct real estate investment would give you more exposure to appreciation.
If you’re looking specifically for depreciation-based tax benefits, an equity real estate investment or a fund structured as a partnership may offer what you need. Flagship Notes’ lending structure intentionally trades those benefits for simpler reporting and more predictable returns.
If you want to pick individual properties and manage deals yourself, a pooled fund structure isn’t going to give you that control.
Those are all valid priorities. They’re just different priorities.
Not sure whether a fixed-income real estate investment fits your goals?
A clarity call is a good place to start. In 30 minutes, we’ll walk you through how Flagship Notes work, how they compare to the fixed-income options you’re already using, and whether this type of structure fits your income needs, timeline, and risk tolerance.
It isn’t a sales call. Our job is to help you understand how Flagship Notes work and give you an honest read on whether this fits your situation, even if the answer is no.
*This material is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy securities. Any offering is made only through applicable offering documents and only to investors who meet applicable suitability and accreditation requirements. Private real estate investments involve significant risks, including illiquidity, loss of principal, lack of diversification, leverage risk, property-level risk, operating risk, sponsor risk, and market risk. Targeted or stated returns are not guaranteed. Past performance, including prior payment history, does not guarantee future results. Investors should consult their legal, tax, and financial advisors before investing.