Most people who invest in apartments follow the same line of thinking. Everyone needs a place to live, so a full building should keep paying its investors even when the economy slows. The demand is certainly there. With the high cost of buying a home pushing more people to rent, apartment households grew by a record 784,000 over the year ending in mid-2025.
Yet many apartment investors lost money anyway, because the cost of owning a building rose faster than the rent coming in. If you invest in multifamily real estate without buying and running a building yourself, someone else makes the decisions that determine whether a deal can handle rising costs like loan payments, insurance, and payroll.
We’ll walk through the main ways to invest without becoming a landlord, what the last few years showed about how these deals hold up, and the questions I’d ask about the people making those decisions before you commit.
How to invest in multifamily real estate without becoming a landlord
You don’t have to buy or manage a building to invest in apartments. There are several ways in, and how you get paid depends on which one you choose.
What is multifamily real estate?
Multifamily real estate is housing with more than one unit under one roof, from a duplex to a 300-unit apartment complex. Lenders treat buildings with five or more units as commercial property, while two to four units are generally financed more like a house. Most passive multifamily investments involve the larger buildings.
Who can invest in private multifamily deals?
Most private apartment investments, including syndications, private funds, and lending funds, are open only to accredited investors. For individuals, that generally means earning more than $200,000 a year, or $300,000 with a spouse, for the past two years, or having a net worth over $1 million not counting your home. Public REITs are the exception, since anyone with a brokerage account can buy shares.
Multifamily syndications: own a piece of one building
In a syndication, a sponsor finds a specific building, arranges the loan, and raises the rest of the purchase money from a group of investors. You read the offering documents, sign a subscription agreement, and wire your investment, and the sponsor runs the property from there.
You’re a part-owner. Rent pays the building’s expenses and the mortgage first, and if there’s cash left over, the sponsor may pay it out to investors along the way. Most of the profit usually comes when the building is sold or refinanced, and your money is typically tied up until then, which can mean several years.
Because syndications are usually set up as partnerships, you’ll get a Schedule K-1 at tax time and owe tax on your share of the income whether or not it was paid out to you. Depreciation from the building often offsets some of that income, which is one reason apartment syndications appeal to high earners. Your tax advisor can tell you how that plays out in your situation.
Private equity funds: spread your money across several buildings
A private equity fund works like a syndication spread across several buildings. Instead of choosing one property, you’re backing a manager and a strategy, and the manager decides which multifamily properties to buy, how to finance them, and when to sell. You’re still an owner, so you share in the gains and the losses, and you’ll receive a K-1. Many of these funds have a fixed term, typically 7 to 10 years, during which your money generally stays in, while others are open-ended and let you cash out periodically.
Public multifamily REITs: exposure you can sell any day
A REIT is a company that owns real estate and trades on a stock exchange. You can buy shares of a multifamily REIT through a brokerage account for the price of a share and sell them any trading day. To keep their tax status, REITs must pay out at least 90% of their taxable income to shareholders, which is why they’re known for dividends. The trade-off is that the share price moves with stock market swings, even when the buildings themselves are doing fine.
Private lending funds: get paid before owners do
In a lending fund, you’re on the lending side of the deal instead of becoming an owner. The fund lends money to building owners and pays its investors from the interest those borrowers pay. Because owners absorb losses before lenders do, rising costs eat into the owner’s share before they touch the lender, though a deep enough loss can still reach lending investors.
You give up any share of the profit when a building sells. The tax form depends on how the fund is set up: many lending funds are partnerships that send K-1s, while some pay interest reported on a 1099.
Here’s how the options compare, with owning a building yourself included as a reference point.
| Option | Who makes the decisions | What happens to you if costs rise faster than rent | Getting your money out |
|---|---|---|---|
| Owning a building yourself | You | You cover any shortfall | Selling the building |
| Multifamily syndication | The sponsor, for one building | Your payouts can stop, and your stake can lose value | Locked until the sponsor sells or refinances |
| Private equity fund | The fund manager, across several buildings | Your payouts can shrink, but other buildings may soften the hit | Set by the fund, often 7 to 10 years |
| Public multifamily REIT | The company’s management | Your dividends and share price can drop | Sell shares any trading day |
| Private lending fund | The fund manager, who chooses the borrowers | You’re paid before the owner, so it takes deeper losses to reach you | Set by the fund’s terms, which vary widely |
Multifamily deals can run into trouble when costs outrun rent
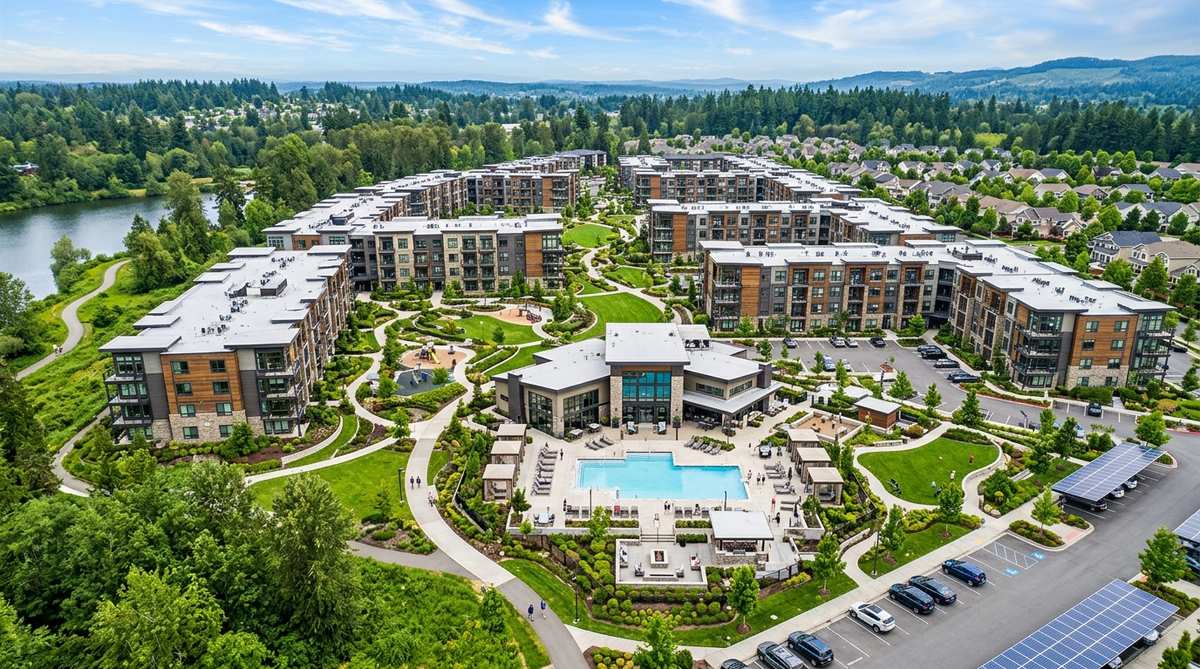
An apartment building can be full and still leave very little for the people who invested in it. That’s what happened to a lot of deals after 2022, and it shows why the structure you choose and the people running the deal matter so much.
Several costs climbed at the same time
Rates rose sharply. Starting in early 2022, the Federal Reserve raised its benchmark rate by 5.25 percentage points in about a year and a half. Owners with variable-rate loans saw their payments jump, and owners who needed to refinance faced much higher rates.
Insurance climbed too. After adjusting for inflation, the typical apartment insurance bill rose about 76% per unit between 2019 and 2024. By then, insurance was eating up nearly 5% of revenue, up from under 3% in 2019. We’ve watched payroll and repair costs rise too.
Rent didn’t keep pace. In September 2026, national asking rents were up just 0.7% from a year earlier, and in major rental markets like Austin and Houston they were lower than the year before.
Rising costs show up first as missed loan payments
You can see the result of these rising costs in how many owners fell behind on their loans. Among apartment loans that lenders bundle and sell to bond investors, 8.04% were behind on payments in September 2026, up from 6.59% a year earlier.
Apartment loans that banks kept on their own books held up much better, with just 1.41% behind on payments in the second quarter of 2026, though that’s still well above where bank loans stood before 2020. So the trouble wasn’t necessarily apartments as a whole. It’s mostly concentrated in particular deals and the loans behind them, which is why the details of any deal you invest in matter so much.
None of this happened because people stopped renting. And I don’t put it all on the operators, either, because nobody had a crystal ball for how fast these costs would climb. But some deals were built with room to absorb a surprise, and some had none.
Five questions that show whether someone built cushion into your apartment deal
Whichever investment route you choose, you’re relying on someone else’s choices. These questions help you judge those choices before you commit, whether you’re reading a syndication pitch, a fund’s materials, or any other private real estate investment.
1. How did their apartments hold up from 2022 on? Every apartment operator went through the same rise in costs, which makes this the most revealing question you can ask right now. Ask what happened to their buildings, what they changed, and whether any investors lost money. A clear, specific answer tells you more about who they are than a polished track record slide.
- . Why this market, and how well do they know it? A national headline can’t tell you how one building will do. In 2024, apartment owners in Orlando paid about $95 per unit each month for insurance, compared with about $50 in Cincinnati, so two buildings with the same rents could leave very different amounts for investors. The operators I trust most stick to a certain size of building in a few states, where they know what rent, insurance, and repairs actually cost.
3. What happens to the numbers if costs rise or rents stall? Ask the operator to show you what happens to your payouts if insurance and payroll cost more than planned, the loan rate goes up, or rents grow more slowly than expected. If the deal still pays investors in that scenario, there’s room for a surprise. If it only works when everything goes right, you carry the risk when something doesn’t.
4. When does the loan come due, and is the rate fixed? On many variable-rate apartment loans, payments rise and fall with a benchmark rate. They’re cheaper when rates are low, but payments can jump quickly when rates rise, as many owners learned after 2022. A loan that comes due in a few years forces the owner to refinance on whatever terms are available at that point in time, and the operator should be able to explain how they’d handle both.
5. Whose money stands in front of yours? Ask whether the operator has their own money in the deal, and where you stand if the property ends up worth less than expected. Owners absorb losses before lenders do, though a deep enough loss can reach lenders too. Know which position you’re in before you invest.
Freedom Notes: Multifamily income with room built in for rising costs
Freedom Notes are a private lending fund. We lend to owners and operators of apartment communities, senior housing, and self-storage facilities. We choose the market, the building, and the operator, so here’s what we look for when we make those calls.
Operators who know their own markets. We lend to operators who focus on one type of property in a handful of markets, so they know local rents and costs firsthand. No loan goes out until the operator clears our 44-point review, and if something in a deal changes late, we’re willing to walk away, even days before it closes.
Room between what a project earns and what you’re paid. The projects we lend on are planned to earn roughly 20% to 22%, and Freedom Notes investors may target 8% to 14%, depending on how much you invest and which track you choose. That difference is designed to cover rising costs like a bigger insurance bill, higher payroll, or a jump in interest costs before your return is affected. All investments in private placements involve risk, including possible loss of principal.
A fixed return that doesn’t wait on a sale. Many multifamily investments save their biggest payout for the day the building sells. Freedom Notes are designed to pay a fixed rate, set when you invest, either as quarterly distributions or compounding on the growth track. We invest our own money in the same deals, and the structure is designed to pay investors before FFI takes its share.
A yearly exit and a simpler tax form. Syndications often hold your money until the sponsor sells. Freedom Notes let you exit once a year, beginning in your first year. Your income shows up on a 1099, not a K-1, and your tax advisor can walk you through what that means for you.
FFI has operated for more than 17 years with no missed investor payouts to date, according to Freedom Family Investments. Past performance does not guarantee future results.
The trade-off is control. You won’t pick the city, the building, or the operator, and you won’t share in the gains if a property we lend on sells for far more than expected. That’s by design, because a note is built for steady income rather than upside.
Who this may not be right for
Freedom Notes won’t fit every investor’s plans for multifamily.
If you’d rather own a building and call the shots, direct ownership gives you control no fund can. The tenants, repairs, financing, and every rising bill come with it.
If you’re hoping to profit when a building’s value goes up, a syndication or equity fund is built for that upside. A note’s rate stays the same no matter what the building sells for.
Apartment owners often use depreciation to lower their tax bill. If that’s a big part of your plan, you’ll want an ownership stake, since a note pays interest and passes no depreciation through to you.
And if you might need your money on short notice, a REIT you can sell on any trading day will suit you better than an investment you can only exit once a year.
Thinking about adding multifamily real estate to your portfolio?
If you’re weighing apartment investments and want a second set of eyes, we offer a 30-minute conversation with our team. We’ll explain how we choose the operators and deals behind Freedom Notes and answer whatever questions you bring.
It isn’t a sales call. The goal is to help you understand how Freedom Notes work and give you an honest read on whether this fits your situation, even if the answer is no.